What is IRS 5498?
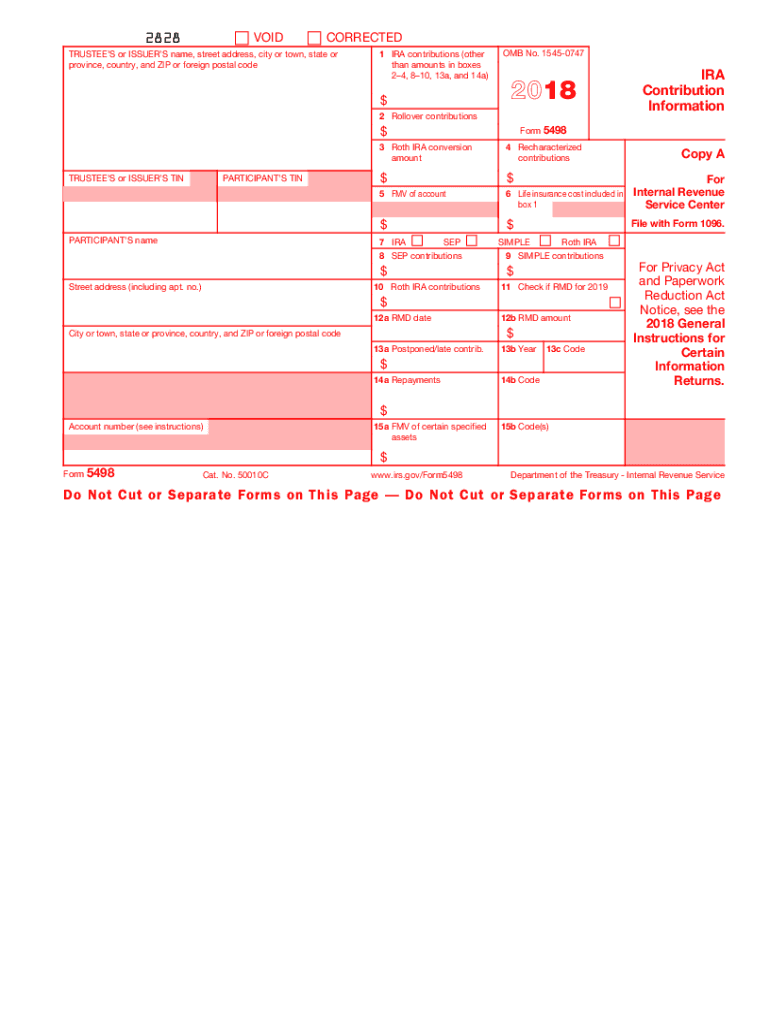
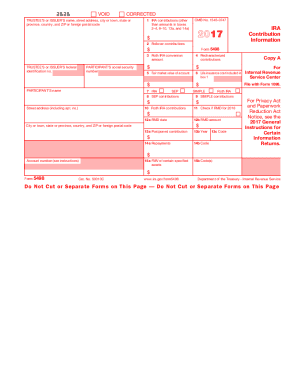
IRS 5498 is a tax form used to report contributions to Individual Retirement Accounts (IRAs) and other types of tax-advantaged accounts. It is essential for taxpayers who made contributions during the tax year as it provides the IRS with necessary information to track retirement savings.
Who needs the form?
Taxpayers who contributed to traditional IRAs, Roth IRAs, simplified employee pension (SEP) IRAs, or savings incentive match plans for employees (SIMPLE) IRAs need to be aware of IRS 5498. Additionally, financial institutions or custodians that manage these accounts are responsible for completing and filing this form.
Components of the form
The main components of IRS 5498 include various boxes to record personal information, contribution amounts, and types of contributions. Key sections also indicate the fair market value of your account and whether required minimum distributions were taken. Understanding these components helps ensure accurate reporting.
Form vs. Form
IRS 5498 should not be confused with other tax forms that report different aspects of financial activity. For instance, Form 1099-R is used to report distributions from retirement accounts, while IRS 5498 is specifically for reporting contributions. Understanding this distinction is crucial for proper tax reporting.
What are the penalties for not issuing the form?
Failure to issue IRS 5498 can lead to penalties imposed by the IRS. Institutions that do not file the form may be fined up to $260 per form. This can add up significantly if multiple forms are not submitted, emphasizing the need for compliance by custodians and financial institutions.
Is the form accompanied by other forms?
IRS 5498 may be submitted alongside other forms, particularly if you are dealing with IRAs and need to report distributions or other associated transactions. However, it primarily functions as a standalone document for contribution reporting.
Where do I send the form?
IRS 5498 is usually filed by the financial institution managing the IRA. If you need to send a copy for your records or corrections, consult the IRS instructions for guidance on where to mail any necessary documentation related to your IRA assets.
What is the purpose of this form?
The purpose of IRS 5498 is to report various types of contributions made to IRAs, including Regular Contributions, Rollovers, and conversions to Roth IRAs. This information helps the IRS verify that taxpayers are meeting contribution limits and encourages compliance with tax laws.
When am I exempt from filling out this form?
You may be exempt from filing IRS 5498 if you did not make any contributions or transactions within the reporting year related to your IRA accounts. Individuals who solely have employer-sponsored retirement plans without making contributions to individual IRAs are also exempt.
Due date
IRS 5498 does not have a traditional filing deadline for taxpayers since the institutions are responsible for reporting the information to the IRS. However, the forms are typically required to be filed by May 31 of the year following the tax year for which contributions are reported. Keep this in mind to ensure compliance.
What payments and purchases are reported?
IRS 5498 reports specific payments such as contributions made to IRAs, including direct deposits and rollovers. Any transactions involving the acquisition of assets for the account may also need to be reported, depending on specific circumstances.
How many copies of the form should I complete?
Typically, financial institutions complete IRS 5498 once for each taxpayer who has a reportable account. However, if you are filing a correction or need additional records, ensure that each version is accurately completed to reflect the correct reporting for the relevant tax year.
What information do you need when you file the form?
When completing IRS 5498, you will need essential information such as the account holder's Social Security number, account details, contribution amounts, and any rollovers or conversions to Roth IRAs. Accurate recording of each aspect is vital to avoid discrepancies with the IRS.