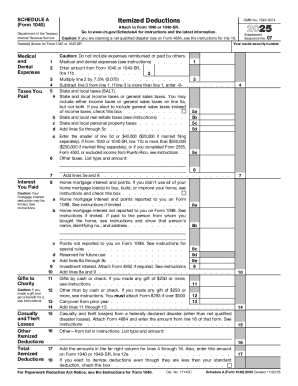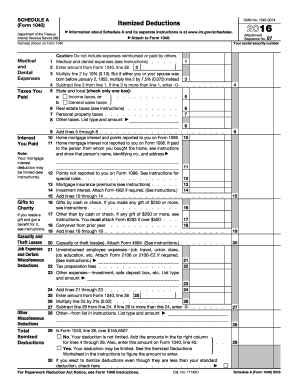
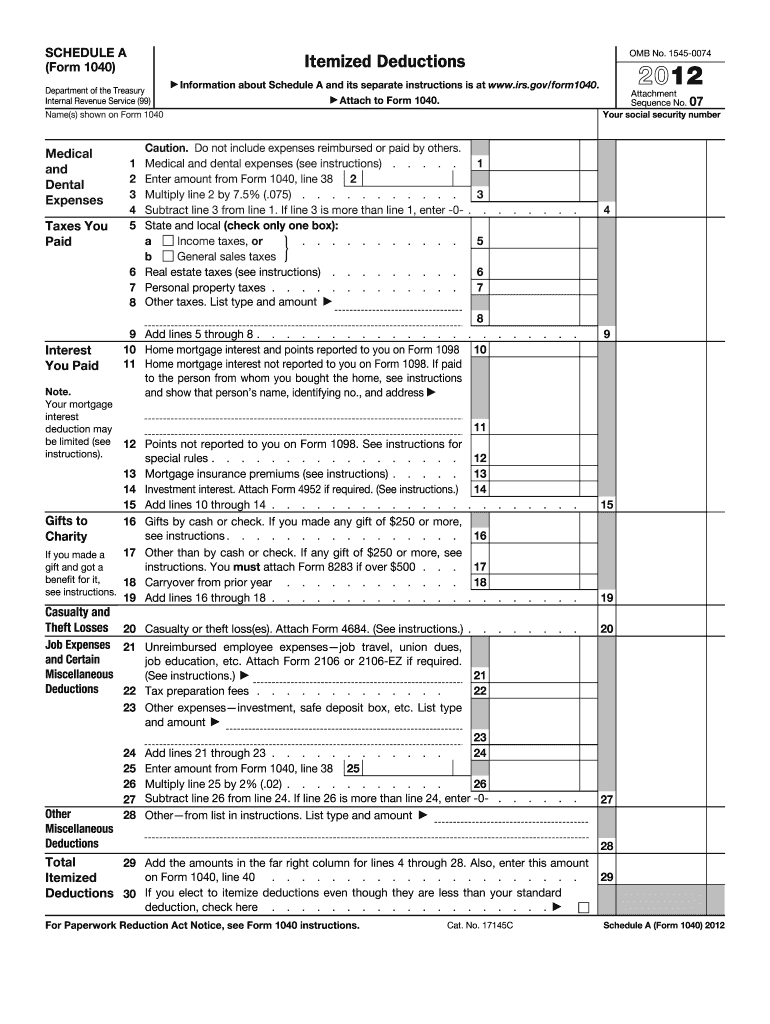
IRS 1040 - Schedule A 2012 free printable template
Get, Create, Make, and Sign IRS 1040 - Schedule A
Instructions and Help about IRS 1040 - Schedule A
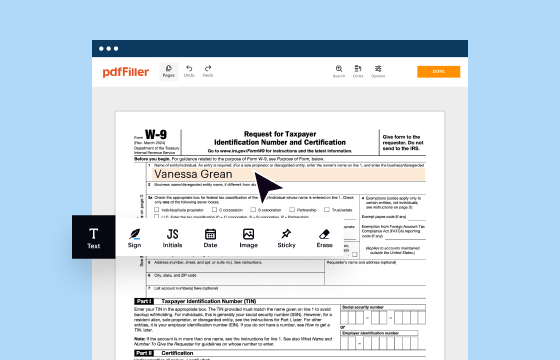
How to edit IRS 1040 - Schedule A
How to fill out IRS 1040 - Schedule A
About IRS 1040 - Schedule A 2012 previous version
What is IRS 1040 - Schedule A?
When am I exempt from filling out this form?
What payments and purchases are reported?
What information do you need when you file the form?
Where do I send the form?
What is the purpose of this form?
Who needs the form?
Components of the form
What are the penalties for not issuing the form?
Is the form accompanied by other forms?
FAQ about IRS 1040 - Schedule A
How can I correct a mistake on a filed schedule a 2012 form?
To correct a mistake on a filed schedule a 2012 form, you need to submit an amended return. Use the appropriate IRS form for amendments and include explanations for the changes. Ensure you keep records of both the original and corrected submissions for your files.
What should I do if my electronic submission of the schedule a 2012 form is rejected?
If your electronic submission of the schedule a 2012 form is rejected, review the rejection codes provided in the notification. Correct any issues and resubmit the form. Keeping an eye on your filing software's requirements may help prevent common errors that lead to rejections.
How long should I retain records related to my schedule a 2012 form?
It is advisable to retain records related to your schedule a 2012 form for at least three years from the date you filed the form. This retention period helps in addressing any potential audits or inquiries from the IRS.
Is it acceptable to use an electronic signature for the schedule a 2012 form?
Yes, electronic signatures are generally acceptable for filing the schedule a 2012 form electronically. However, ensure that the e-signature complies with IRS regulations as well as any state requirements, if applicable.
What should I do if I receive a notice regarding my schedule a 2012 form?
If you receive a notice regarding your schedule a 2012 form, review the content carefully to understand the issue. Gather the necessary documentation and respond promptly, ensuring you address any questions or concerns raised by the IRS to prevent further complications.
See what our users say